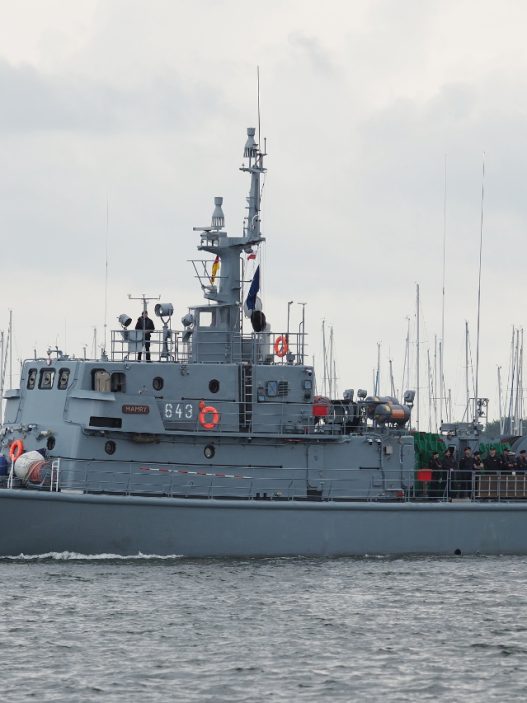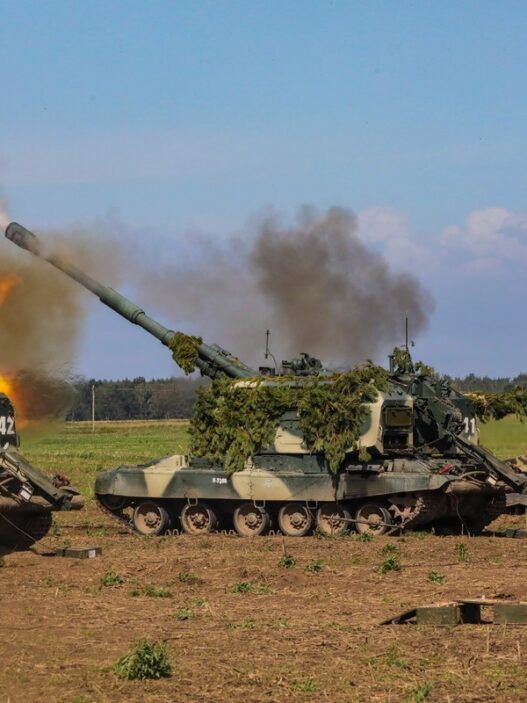






Europe is rearming at a pace not seen since the Cold War. In 2024 alone, military spending across Europe rose by 17%, reaching a record $693 billion, a level last witnessed in the early 1980s. Germany became the fourth-largest spender globally, and every European country increased its military budget, except Malta. Politically, the urgency to invest in defense is presented as both a matter of necessity and sovereignty. Across capitals, the war in Ukraine has become the accelerant for an industrial revival, couched in terms of “strategic autonomy” and “economic security.” Yet beneath the headlines, this revival is far from frictionless, and it is unlikely to unfold as a traditional job boom.
The narrative of defense-led reindustrialization resonates with older visions of wartime mobilization: factories humming, supply chains rerouted domestically, and a renewed demand for skilled, well-paid manual labor. But Europe’s current rearmament is not that. As The Economist recently noted, what is underway may “slow Europe’s deindustrialization, but probably not reverse it”. Even optimistic projections, such as Ernst & Young’s estimate of 500,000 new jobs, would represent just 1.5% of the continent’s manufacturing base, and only a fraction of that will materialize within the defense industry itself.
One of the clearest illustrations of the ambition-versus-reality gap is Germany. Having declared a watershed Zeitenwende in 2022 and committed €100 billion to defense modernization, Berlin is now debating a second fund worth up to €200 billion, not just to buy weapons, but to underwrite an entire military-industrial ecosystem before the political window closes. “We want the ability to defend ourselves in order not to have to,” Chancellor Friedrich Merz stated, reflecting the broader shift in mindset about the continent’s security dependencies. Yet even with political momentum, constitutional limits and coalition tensions threaten to stall delivery on these ambitions.
Meanwhile, the institutional and financial architecture needed to scale up production is still underdeveloped. Europe’s defense small and medium enterprises (SMEs), which account for much of the innovation and specialized capacity, remain chronically underfinanced. According to industry surveys, over half of them avoid applying for bank loans altogether, perceiving the risks as too high and the timelines as too short. This leads to a paradox, as one Financial Times report put it: “Depriving an in-demand industry of cash makes little sense”. The recently proposed European Defence Industry Programme (EDIP) and the European Defence Industry Reinforcement Procurement Act (EDIRPA) aim to address this, but both remain politically fragile and insufficient to close the annual financing gap, let alone enable large-scale defense autonomy. 
Yet even these constraints do not fully explain the deeper structural feature of Europe’s rearmament: it is not a centralized mobilization effort, but a fragmented, market-based integration project. As Kaija Schilde has shown, the EU’s approach to defense integration is rooted in its broader political economy, one that privileges supply chains, market regulation, and embedded neoliberalism over the classic military-industrial complex. The EU integrates through defense markets, not through defense ministries. Rather than building a singular European army or state-directed production base, it fosters horizontal industrial coordination under strategic pretenses.
This industrial logic finds its justification in the broader geoeconomic turn of EU policymaking. According to Matthijs and Meunier, the EU is undergoing a profound transformation from a regulatory superpower to a geoeconomic actor that sees economic tools as essential to geopolitical leverage. Defense autonomy is no longer just about threat response; it is about securing Europe’s position in a world where interdependence has become vulnerability. The defense industry is thus framed not only as a security asset but as a pillar of economic resilience, technological innovation, and regional cohesion.
The paradox is clear: Europe is spending more on defense, demanding more from its industries, and promising more to its citizens, but without the centralized institutions or traditional economic benefits that such a mobilization implies. Instead, what is emerging is a hybrid model: part market, part mission; part sovereignty, part subcontracting; and deeply constrained by structural inefficiencies. The result may still be a stronger European defense base, though not necessarily a more inclusive or labor-intensive one. That tension lies at the heart of the labor promise that politicians now promote.
Robots don’t vote, but they still change politics
As Europe pours billions into defense reindustrialization, many policymakers promise a renaissance of skilled, “real economy” jobs. In Germany, defense investments have been tied to a revival of the Mittelstand, the country’s ecosystem of small and medium-sized industrial firms, and long-term youth employment strategies. At the EU level, officials frame this push as part of a sovereignty transition that complements the green and digital transformations. Yet behind this rhetoric lies a quieter reality: the modern defense industry is neither labour-intensive nor broadly inclusive.
According to CEDEFOP, many of the production jobs typically associated with manufacturing, like welding, assembly-line machining, and metal treatment, fall into the high-automation-risk category, especially in technologically advanced sectors like aerospace, armaments, and autonomous systems. While older defense economies relied on large, manual labour forces for shipbuilding or armoured vehicle production, contemporary defense manufacturing increasingly involves digitally controlled, high-precision systems often run by a small number of highly specialized technicians. These trends are visible across Europe: drone production lines in Latvia and Slovakia, for example, are highly automated and require only a fraction of the staff needed for traditional systems like tanks or submarines.
The EU’s own 2019 defense skills vision recognized the structural shift. It warned that, unlike other industrial domains, defense jobs tend to be highly technical, security-vetted, and difficult to scale without targeted training investment. The document also highlighted how persistent “bottlenecks” in digital engineering, cybersecurity, and systems integration are exacerbated by Europe’s fragmented industrial base, making it harder to match young labor to industrial demand. This is not just a skills gap but a structural mismatch between the labor narrative and actual production needs.
RAND’s assessment echoes this concern: Europe’s defense sector is constrained not just by budgetary cycles but by a shortage of key competencies such as systems engineers and AI coders, additive manufacturing specialists, and high-grade welders. These professions take years to train and are often underpaid compared to the private tech sector. Attracting youth to defense manufacturing in this environment remains an uphill battle, especially without clear long-term employment guarantees.
Some national governments have responded with vocational training initiatives linked to defense industrial projects. France’s state-backed programs in the Occitanie region have focused on integrating apprenticeships into aerospace and drone production; Germany’s Rheinmetall has partnered with regional technical schools to fast-track mechanical engineers and defense-capable CNC machinists. However, these programs are relatively new, small in scale, and unevenly distributed across the continent. Southern and Eastern European countries, often touted as future hubs for low-cost defense production, lack the institutional infrastructure to replicate such models at speed.
Even where training systems exist, they are often disconnected from actual defense procurement cycles. The OECD has highlighted how vocational education and training (VET) systems in Europe still struggle to align curricula with fast-evolving industrial technologies, especially in sectors subject to export controls, dual-use restrictions, and rapid digitalization. In many cases, jobs are promised before factories are built, and factories are designed before skills are available.
This structural lag has consequences. While the EU continues to argue that defense reindustrialization is an engine for strategic autonomy, it risks creating what could be called an industrial “legitimacy gap”: rising budgets and infrastructure spending without the broad-based employment outcomes that would politically legitimize them. CEDEFOP and Eurostat data suggest that most of the new defense-related employment will be concentrated in a handful of high-skill clusters, leaving large regions and traditional blue-collar constituencies behind.
For Europe’s political class, this is an uncomfortable truth. Defense policy has historically been a top-down, elite-driven field. But once framed as economic policy, as it now increasingly is again, it enters a different realm of public scrutiny. If voters are promised jobs, they expect them. If factories are announced but few locals are hired, disillusionment can quickly follow. And if autonomy becomes automation, the EU may find itself defending sovereignty with tools that don’t deliver the democratic buy-in it needs.
Strategy Autonomy meets Social Reality
The EU’s defense reindustrialization drive rests on a powerful ambition: to secure Europe’s strategic autonomy in a world where supply chains, alliances, and deterrence are no longer guaranteed. Yet as this ambition accelerates, a central contradiction emerges. While billions are being channelled into defense production, R&D, and joint procurement, the promised dividends in terms of jobs, regional revitalization, or public legitimacy remain uneven if not illusory.
This article so far has laid bare the contours of this paradox. On the one hand, the EU is expanding its defense-industrial base through initiatives like the European Defence Fund (EDF), the Act in Support of Ammunition Production (ASAP), and EDIRPA. Member states such as Germany and France are rearming on a scale not seen since the Cold War. Yet as the RAND Corporation has shown, the labor needs of modern defense industries are highly specialized, often geared toward niche technical skills or automated systems that require years of targeted education, not mass hiring.
As a result, the strategic push risks becoming unmoored from its social foundations. Research by Koenig warns of a “legitimacy trap”, where security policy is driven by elite consensus but lacks societal buy-in. The public may support defense spending in the abstract, especially after Russia’s invasion of Ukraine, but such support will likely prove brittle if investments yield few visible returns in employment or regional equity.
To reconcile this gap, the EU must redefine what success looks like. Rather than measuring reindustrialization purely in job creation or output volumes, policymakers should adopt a broader metric of strategic resilience: the ability of European states to maintain critical capabilities, absorb shocks, and reduce dependency on foreign suppliers. Bruegel’s early work on industrial strategy anticipated this shift by calling for policy metrics that go beyond employment, toward innovation ecosystems, supply chain robustness, and societal inclusiveness.
This would mean, for instance, assessing how EDF funding supports not just large defense primes but also SMEs and dual-use innovators across member states. It would also mean tracking vocational pathways and skills development pipelines, especially in regions that risk being left behind. As the European External Actions Service’s strategy updates now recognize, resilience is as much about who is included in the defense economy as it is about what is produced.
Forward-looking policy will require more than just new metrics; it will require new institutions and coordination. Proposals such as a European Defense Skills Observatory or regional industrial-labor task forces could help bridge the gap between investment and inclusion. Fontana and Vannuccini’s recent analysis points to the need for institutional continuity in EU defense planning, not just ad hoc crisis responses, but long-term ecosystems that link sovereignty, skills, and strategic planning.
Public communication will also matter. Europe’s defense rearmament is often framed in bureaucratic language like capability gaps, interoperability, and strategic enablers. Yet for most citizens, what matters is whether these efforts make them safer, more included, and more economically secure. Without this connection, the EU risks winning the battle of autonomy while losing the political consensus needed to sustain it. Reindustrialization must serve more than security. It must serve society.