





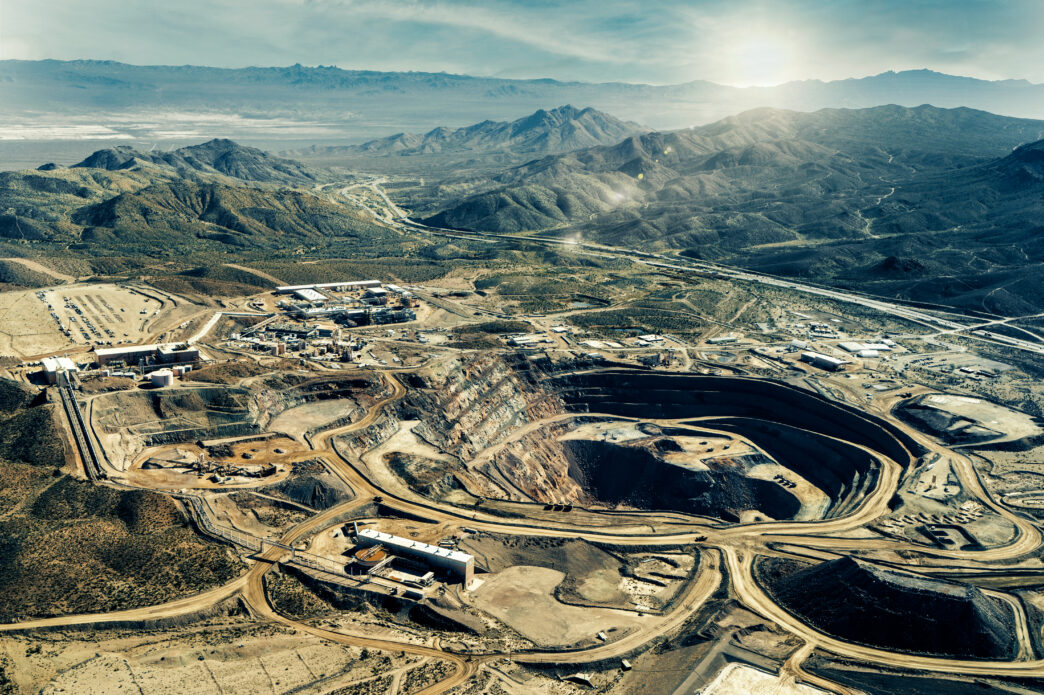
“Whoever controls the supply of rare earths controls the world.” This oft-cited phrase, attributed to Deng Xiaoping in the early 1990s, has aged with uncanny precision. In today’s geopolitics, obscure-sounding materials like neodymium, dysprosium, or terbium are no longer just industrial inputs. They are critical enablers of the green transition and silent cornerstones of digital, military, and energy infrastructures.
Nowhere is this strategic relevance more pronounced than in the European Union. As the EU races to meet its net-zero targets, its dependence on imports of rare earths, over 90% of which come from China, risks undermining both its climate ambitions and industrial resilience. The adoption of the Critical Raw Materials Act (CRMA) in 2023 marked a turning point in Europe’s attempt to address this vulnerability. But with rising global demand, China’s tightening export controls and limited domestic capacity, the bloc faces a tough balancing act: reduce dependency without derailing decarbonization.
This article explores how rare earths are reshaping EU-China relations, placing the question of strategic autonomy at the core of Europe’s green transition. Can the EU secure the materials it needs without falling into a new form of dependency? And if not, what kind of geopolitical position is Europe headed for?
Europe’s Green Dependency 
To understand Europe’s current vulnerability, it helps to start with what rare earth elements actually are and what they’re not. Despite the name, they are not inherently rare in nature. Rather, they are difficult to extract and process economically, often occurring in trace amounts across different minerals. Their strategic value comes from what they enable: from wind turbines and electric vehicle motors to smartphones, semiconductors, and military sensors. Without rare earths, there is no digital economy, and no green transition.
Yet the European Union currently has little control over these critical building blocks. According to the European Commission, the EU relies on China for over 98% of its rare earth permanent magnet imports, the high-demand components used in motors and generators. When it comes to heavy rare earth elements like dysprosium or terbium, the EU’s dependency on Chinese processing is close to absolute. Even for lithium, essential for battery production, the EU forecasts a twelve-fold increase in demand by 2030, rising to twenty-one-fold by 2050.
In response, the EU adopted the CRMA in 2023, setting ambitious targets: at least 10% of annual consumption should be extracted domestically, 40% processed, and 25% recycled, all by 2030. But turning targets into capabilities is proving difficult. The EU’s mining capacity remains fragmented, and environmental resistance to domestic extraction, particularly in member states like France and Germany, has slowed the rollout of new projects.
In the meantime, the urgency of the green transition continues to outpace the EU’s ability to localize its supply chains. The dilemma is stark: Europe’s climate strategy is built on materials it does not control, sourced from a country it increasingly sees as a systemic rival. This dependency is not just economic but geopolitical.
China’s Leverage & Resource Weaponization
Beijing has long understood that rare earths are more than just industrial inputs, rather they are levers of strategic power. When former Chinese leader Deng Xiaoping declared in the 1990s that “the Middle East has oil, China has rare earths,” it was not just a reflection of resource abundance, but a preview of a deliberate geopolitical posture. Today, that posture is becoming clearer.
In recent years, China has repeatedly used export controls on rare earth materials to pressure foreign governments and protect its own supply chains. In 2023, the government imposed licensing restrictions on gallium and germanium, both key materials for semiconductors and solar cells, citing national security concerns. The following year, it expanded those controls to include rare earth magnet exports, directly affecting European electric vehicle production. Industry leaders in Brussels warned that delays in securing licenses were already causing disruptions for EU manufacturers.
These moves echo China’s earlier playbook. In 2010, Beijing sharply reduced rare earth exports to Japan during a maritime dispute, a decision that triggered WTO challenges and prompted years of global investment in alternative sources. Today’s environment, however, is different. Global demand has soared, while China still dominates 70–90% of global refining capacity for most rare earths. Even where extraction occurs elsewhere, the critical processing phase remains largely under Chinese control.
From Beijing’s perspective, this is a form of strategic insurance. As Trivium China analysts noted, future restrictions on materials like graphite or antimony may become tools in wider trade disputes, or responses to Western export bans on advanced tech. Meanwhile, Chinese firms have also expanded aggressively abroad, from Indonesia to Africa, often gaining privileged access to new mineral reserves.
For Europe, this raises the stakes significantly. Rare earths are no longer just a matter of price or efficiency, they are a question of vulnerability in a world of sharpened economic statecraft. As Chinese export policy becomes more strategic and less predictable, the EU’s dependency looks increasingly like a liability in waiting.
The EU Response: Strategic Plans, Mixed Realities
The European Union has not been blind to the strategic risks of resource dependency. With the launch of the CRMA in 2023, Brussels signaled a clear shift from market liberalism to a more active industrial strategy. The Act lays out binding benchmarks for 2030: at least 10% of annual critical raw material consumption should be mined within the EU, 40% processed, and 25% recycled. The goal is not full self-sufficiency, which experts widely agree is unrealistic, but resilience through diversification.
Early steps have been taken. In March 2025, the European Commission approved 47 strategic projects across 13 member states, streamlining permitting procedures and offering financial backing via the European Investment Bank and the European Bank for Reconstruction and Development. One standout initiative is Solvay’s expansion in France, which aims to meet 30% of the EU’s rare earth magnet needs by 2030.
But progress is uneven. While the CRMA has provided a legal framework, turning it into material reality requires time, coordination, and political will. Member states retain control over permitting, often facing public resistance to mining projects on environmental grounds. A proposed gallium extraction project in Greece, for instance, triggered significant local opposition despite being labelled a strategic priority. Moreover, as Commissioner Stéphane Séjourné recently warned, the EU lacks adequate strategic reserves of rare earths, leaving it vulnerable to sudden disruptions.
Another limitation is scale. Even if the EU meets all CRMA targets by 2030, it would still cover only a fraction of its projected demand. Lithium demand alone is expected to grow more than twentyfold by mid-century. And many of the most critical processing capabilities remain outside the bloc, with China maintaining global dominance over refining and separation.
In short, the EU has made the right diagnosis, but the cure remains partial. It has a plan, but not yet the means to match the ambition. The race between regulatory timelines and geopolitical reality is still wide open.
Global South Partnerships & Geopolitical Dilemmas
Europe has recognized that building resilience requires reaching beyond its borders. Over the past two years, Brussels has woven critical mine partnerships into its Global Gateway and Minerals Security Partnership agendas. But while these deals signal intent, they also expose the limits of diversification.
In Namibia, a provisional deal back in 2022 offers preferential EU access to dysprosium and terbium, essential magnets for EVs and wind turbines. This was followed by a €1 billion investment under Global Gateway in 2023 to develop sustainable raw-material supply chains and green hydrogen links.
Central Asia, especially Kazakhstan, has emerged as another focus area. In March 2025, the EU signed multiple agreements (totaling over €3 million) coordinated by the European Bank for Reconstruction and Development to finance critical-minerals extraction, positioning Kazakhstan as a potential West-aligned rare earth supplier. Despite early enthusiasm, nearly 100 % of Kazakh output still flows to China as today’s partnerships lack the structural levers to redirect production.
These deals are part of a broader diplomatic thrust: the EU’s 2025 Central Asia summit branded Eurasian partners as more “reliable”, with €2.5 billion earmarked for raw-material cooperation to shift sourcing away from China
Yet the divergence between ambition and reality is stark. Kazakhstan may have Europe’s potentially third-largest rare earth deposit, Zhana Kazakhstan, but lacks downstream infrastructure, and Chinese entities retained full export control as late as 2024. In Namibia, local governance challenges and environmental scrutiny risk delaying projects. Meanwhile, nascent ventures in Indonesia and Australia are years away from being scaled to EU levels.
There are also ESG trade-offs. Many Global South suppliers face pressures to balance environmental protection with export revenues, raising concerns about standards oversight and reputational risk for the EU.
Hence, while Europe is deploying a multi-corridor strategy, the result is more nascent network than secure supply chain. Without major breakthroughs in permitting, processing capacity, and trade volumes, these partnerships remain gestures of intent rather than real hedges.
Conclusion: Whats at stake for the EU?
Rare earths may seem like technical inputs buried deep underground and tucked away in the wiring of future technologies, but they are fast becoming litmus tests of global power. For the European Union, they expose the deep contradiction between ambition and dependency: the bloc seeks strategic autonomy while remaining reliant on a single country for materials central to its industrial and green transformation.
China’s willingness to weaponize its resource dominance has made this challenge urgent. The EU’s response is a step in the right direction. Yet time, capacity, and coordination remain significant hurdles. Even the most promising initiatives can be undermined by sluggish permitting, fragile foreign partnerships, or continued processing bottlenecks.
At its core, this is more than a supply chain problem, it is a question of agency. If the EU is to credibly position itself as a global geopolitical actor, it must ensure that its green ambitions are backed by secure, sustainable, and diversified access to the raw materials that power them. Otherwise, the promise of European sovereignty risks becoming entangled in dependencies it set out to overcome.
What comes next will depend not only on Brussels’ strategic foresight, but on its ability to turn frameworks into facts and partnerships into production.